 Proud member of the Federation of Damp

Does Home Insurance Cover Rising Damp?
Updated 5 November 2026. Reviewed by Michael Young, Head Contractor at Advanced Damp (CSSW and FODCS).
Key Takeaways
- Standard home insurance policies almost never cover rising damp, because insurers treat it as gradual deterioration rather than sudden damage.
- Damage caused by a sudden event, such as a burst pipe or storm damage, is often covered, even if it leaves the walls damp.
- Penetrating damp is usually excluded too, unless it was caused by a specific insured event like storm damage to a roof.
- If damp was missed when you bought, a valid guarantee from previous treatment, or a claim against the surveyor, may be better routes than your insurer.
- Getting the cause diagnosed properly helps either way: it shows whether there is an insured event behind the damp, and stops money being spent on the wrong fix.
Why insurance doesn’t cover rising damp
Home insurance is designed to pay for sudden, unforeseen events. Rising damp is the opposite. It develops slowly over months and years as ground moisture travels up a wall that has no working damp proof course. Almost every buildings policy excludes gradual deterioration, wear and tear and lack of maintenance, and rising damp falls squarely into those exclusions. Insurers also take the view that a homeowner can spot and deal with damp before it causes major damage, so it is treated as a maintenance responsibility rather than an insured risk.
What insurance can cover
Damp is not always excluded. What matters is the cause. If the damp is the result of an insured event, the resulting damage may well be covered.
- Escape of water. A burst or leaking pipe, a failed tank or a leaking appliance that suddenly soaks a wall or ceiling is a standard insured peril, although a slow leak that went unnoticed for months may be disputed.
- Storm damage. If a storm lifts tiles or damages flashings and rain gets in, the resulting damp damage is often covered.
- Flood. Water entering from outside in a flood event is usually covered by buildings insurance, but check the policy wording, particularly for basements.
- Accidental damage. Some policies with accidental damage cover may respond to specific incidents, such as a drill through a pipe.
Even when the cause is covered, insurers usually pay to repair the resulting damage, not to put right underlying defects such as missing damp proofing.
Damp types and how insurers treat them
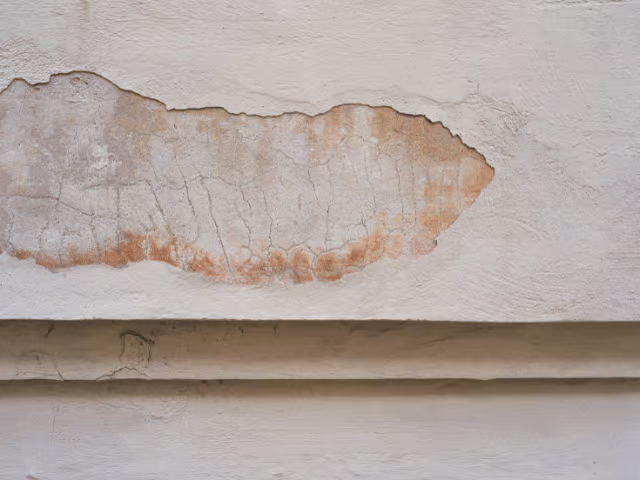
| Damp type | Typical signs | Usually covered? | Why |
|---|---|---|---|
| Rising damp | Tide marks up to around a metre, salts, blown plaster low on walls | No | Gradual deterioration |
| Penetrating damp | Patches that worsen after rain, often higher up walls | Sometimes | Only if caused by an insured event such as storm damage |
| Condensation | Black mould, wet windows, musty smell | No | Treated as a ventilation and living conditions issue |
| Burst pipe | Sudden wet patches, ceiling staining | Usually | Sudden and accidental escape of water |
| Flood water | Rapid water entry in a flood event | Often | Depends on policy wording, check basement cover |
The grey areas
Many disputes come from damp that has more than one cause, or where the timeline is unclear. A slow leak that has been running behind a kitchen unit for a year might be covered as escape of water by one insurer and declined as gradual damage by another. Penetrating damp after a storm may be accepted if the storm damage is clear and recent, but refused if the roof was already in poor condition. In these cases, evidence makes the difference: photographs, dates, moisture readings and a written report explaining the cause carry far more weight than a description over the phone.
What insurers look for when assessing a damp claim
- The cause. Was there a specific insured event, and when did it happen?
- The timeline. Did the damage appear suddenly or develop over time?
- Maintenance. Were gutters, roofs and pipework in reasonable condition beforehand?
- Prompt reporting. Was the problem reported as soon as it was noticed?
- Evidence. Is there a report from a qualified surveyor setting out the cause?
A damp survey by a CSRT qualified surveyor gives you that written evidence, whichever way the claim goes.

If your claim is refused
A refusal from your insurer is not always the end of the road. There are other routes worth checking.
- Existing guarantees. If the property has had damp proofing before, look for the paperwork. Many treatments come with a long-term written guarantee that transfers to new owners, and some are backed by insurance in case the installer has ceased trading.
- Your purchase survey. If you bought recently and a survey failed to mention obvious damp, you may have a claim against the surveyor. Our guide on what to do if a surveyor missed damp explains how that works.
- The seller. If the seller knew about damp and said otherwise in the property information forms, take legal advice about misrepresentation.
- Your landlord. If you rent, damp and repairs are usually the landlord’s responsibility, not yours.
- The Financial Ombudsman Service. If you think an insurer has applied an exclusion unfairly, you can complain to the insurer first and then to the ombudsman.
This is general information, not legal advice. For anything involving a claim against another party, speak to a solicitor.
What rising damp treatment typically costs
Because insurance rarely pays, most homeowners fund rising damp treatment themselves. Typical UK ranges are below, with London prices usually higher.
| Treatment | Typical cost (UK) | Typical cost (London) |
|---|---|---|
| Chemical DPC injection, per 3 m wall | £800 to £1,500 | £1,000 to £2,000 |
| Replastering after DPC, per room | £600 to £1,200 | £800 to £1,500 |
| Full ground floor rising damp treatment | £2,000 to £5,000 | £3,000 to £6,500 |
| Timber treatment to joists and plates | £500 to £2,000 | £700 to £2,500 |
The biggest saving usually comes from diagnosis. Plenty of walls that look like rising damp are actually suffering from rain penetration, condensation or bridging, which cost far less to fix. See what a damp proof injection involves for more on treatment.
Period properties
Victorian and Edwardian homes often have slate or bitumen damp proof courses that have failed, been bridged by raised ground, or been covered by later render. They also tend to have solid walls that are prone to penetrating damp and condensation. That mix makes careful diagnosis especially important, both for treatment and for any conversation with an insurer about the cause.
When to book a damp survey
Book a survey if you are preparing an insurance claim, if a claim has been declined and you want to understand why, if you are buying a property with visible damp, or if you have been offered treatment without a clear explanation of the cause. You can book a damp survey online and we usually respond the same day during working hours.
Frequently asked questions
Is rising damp covered by home insurance?
Almost never. Insurers treat rising damp as gradual deterioration, which is excluded from standard buildings policies. Damage from a sudden event, such as a burst pipe, is a different matter and is often covered.
Is penetrating damp covered by insurance?
Usually not, unless it was caused by a specific insured event such as storm damage to a roof. Penetrating damp from worn pointing, blocked gutters or old render is treated as maintenance.
Is condensation or black mould covered by insurance?
No. Condensation is treated as a ventilation and living conditions issue rather than an insured event. The fix is usually better ventilation, heating and in some cases insulation.
Can I claim against my surveyor for missed damp?
Possibly, if the damp was reasonably visible at the time of the survey and the report did not mention it. You would normally need evidence of when the damp started and what the surveyor should have seen.
Does a damp proofing guarantee transfer when I buy a house?
Many do, but check the paperwork. Ask the seller for the guarantee, confirm which walls it covers, and check whether the installer is still trading or the guarantee is insurance backed.
Should I get a damp survey before making an insurance claim?
It helps. A written report from a qualified surveyor sets out the cause and extent of the damp, which is exactly what an insurer or loss adjuster will want to see.
Reviewed by Michael Young, Head Contractor at Advanced Damp (CSSW and FODCS). Last reviewed November 2026.
Related Case Studies
Our recent work includes lower ground flat, Kings Cross WC1X; entrance party wall, Kilburn NW6 and bay window room, Highbury N5. Each case study sets out what the survey found and how the problem was fixed.
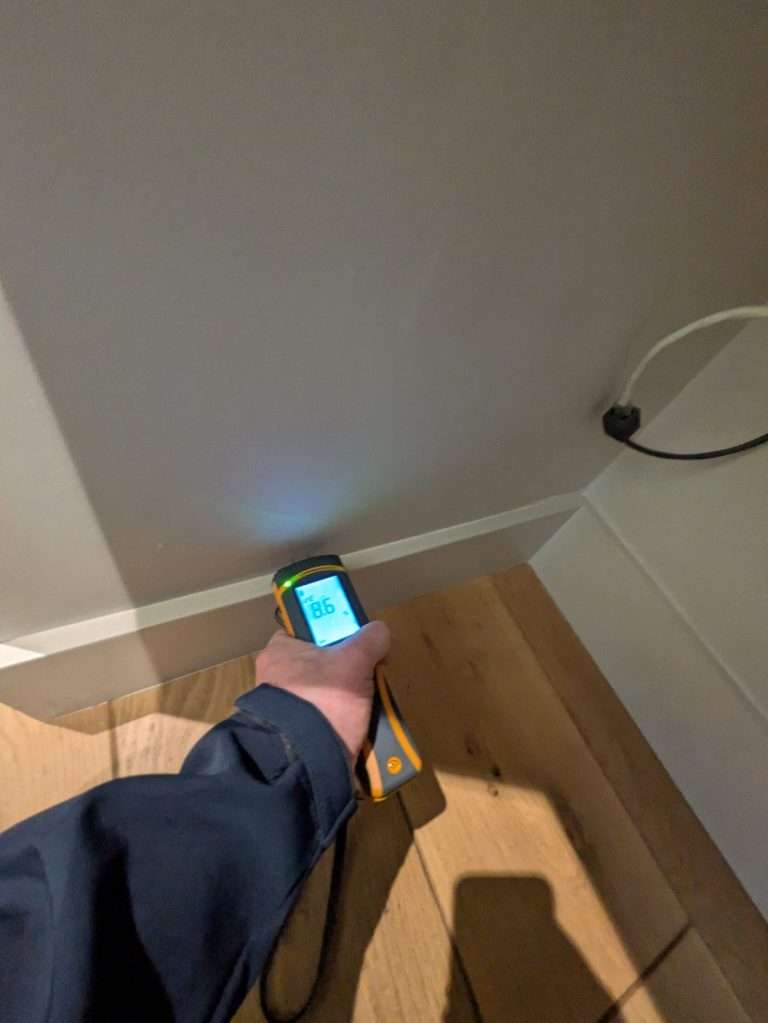
Lower ground flat, Kings Cross WC1X
Rising damp returned around an arch and back door despite an earlier DPC. Treated with a new DPC, waterproof render and skim ahead of a sale.
Read the case study →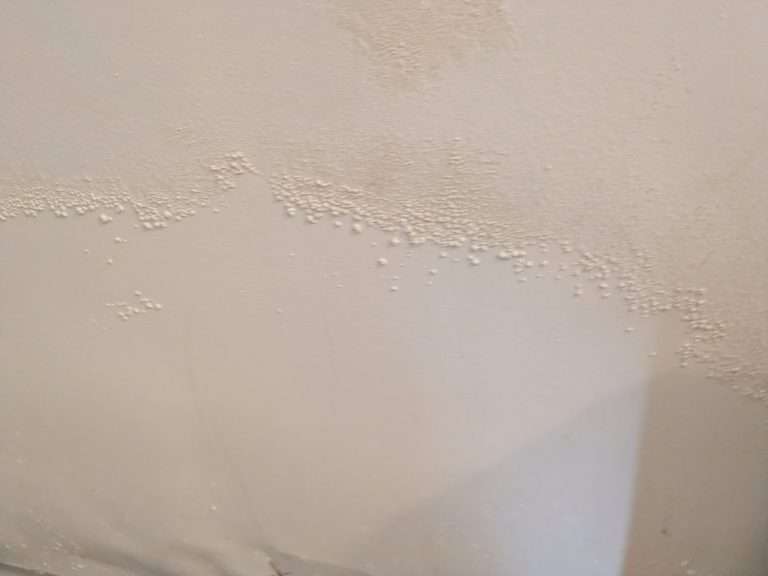
Entrance party wall, Kilburn NW6
A raised front step was bridging the DPC. The party wall was treated with a new DPC, render and set.
Read the case study →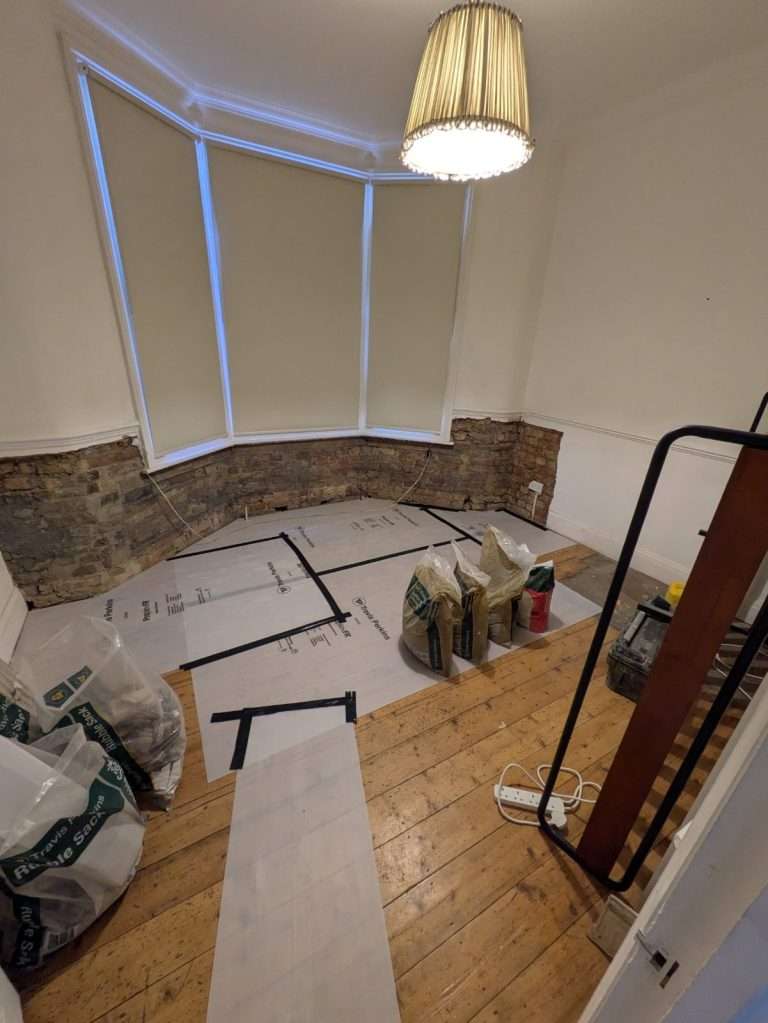
Bay window room, Highbury N5
Two areas of rising damp treated with a new DPC, waterproof render and replaster, with external defects set out for repair.
Read the case study →
Sam Fitzgerald is the founder of Advanced Damp and a working damp and structural waterproofing surveyor diagnosing and treating moisture problems in residential and commercial properties across London and the South East. He is FODCS certified (a Federation of Damp Certified Surveyor) and a member of the Federation of Damp. His hands-on work covers rising damp, penetrating damp, condensation, basement waterproofing to BS 8102, and thermal imaging surveys, and he has personally completed over 400 damp surveys across properties of every type and age. Everything he writes draws directly from jobs he has carried out. He does not write about treatments, products or causes he has not dealt with first-hand in the field.